Women’s Cricket World Cup was great, but Matildas home World Cup will be greater

Last Sunday’s T20 Women’s World Cup final between Australia and India was a fantastic sporting spectacle.

The crowd of over 86,000 at the MCG, the highest attendance for a standalone women’s sporting event in Australia, saw the Aussie side win their fifth T20 World Cup.

The local TV ratings were also impressive, with an average audience of 1.231 million Australians tuning into the match.

While the tournament final was a huge success, it is up for debate whether the previous stages lived up to expectations.

Crowds were small for most of the other games throughout the competition, including only 6,161 showing up to the SCG for a rain affected Australia vs South Africa semi-final.

Australia’s opening match of the tournament against India had 13,432 fans in attendance at the Sydney Showground Stadium, the biggest outside of the final.

In comparison, The Matildas drew a crowd of 14,014 in Newcastle last Friday for an Olympic qualifier against Vietnam.

If Australia and New Zealand do win the right to host the 2023 FIFA Women’s World Cup, it’s safe to say crowd figures will be much more impressive than the T20 Women’s World Cup.

Initial projections in Australia and New Zealand’s joint bid book, claim that over 1.5 million will attend the 2023 tournament with an average crowd of 24,000 per match.

Australia will host 24 games throughout the group stages of the tournament and 11 in the knockout stage, with the final to be held at Stadium Australia in Sydney.

The other stadiums that will be used for the tournament in Australia are: the Melbourne Rectangular Stadium, Brisbane Stadium, Newcastle Stadium, York Park, Perth Oval, the re-developed Sydney Football Stadium and Hindmarsh Stadium.

If the tournament is priced correctly, it’s hard to see Australia’s bid not being extremely successful for women’s sport.

Crowds for Matildas games in a home World Cup will be huge, but there will also be significant interest in other teams competing in the tournament due to our diverse population.

TV ratings will be big in Australia and around the world, although Australia’s time-zone is not exactly favourable for a major event.

Speaking to SBS TWG, Off The Pitch reporter and experienced FIFA and UEFA watcher James Corbett, believes Australia is the favourite.

“If we look at it as a rational open tender process, you’d like to think [that Australia are in front],” Corbett said.

“The Matildas are arguably Australia’s most popular national team and in a competitive domestic sporting culture have brilliantly carved out a place for ’soccer’ in Australia and the country has, in Sam Kerr, one of the best players on the planet.

“The country has the infrastructure to host it; it’s an event that’s far less dependent on TV revenues as a measure of success, so its distance is less of a factor. It is politically and economically stable.”

Corbett believes FFA’s appointment of James Johnson as new CEO will change the perception of Australia’s governing body and their previous administration faults.

“If you look at the political side, where Australia has faltered in the past is a distance between its administrators from the ‘heart and soul’ of the game.

“Previous FFA CEOs and other leading executives have come from other sports and have been considered aloof from their peers in the global game, who ultimately decide these matters.

“The men’s 2022 World Cup bid – which was arrogant and sulphurous – was a case study in how not to bid for a major competition.

“There’s been a realignment with the true values of football in recent years, and the FFA’s new CEO, James Johnston, has worked for both FIFA and the AFC and knows which buttons to push, as well as being tremendously engaging and good at his job.

“Former Matilda, Moya Dodd, is arguably one of the most powerful people in women’s football worldwide and will know how to navigate the committee rooms.”

This past week the FFA announced that there was an 11% increase in participation in 2019 for women and girls playing the sport of Football in Australia.

These are important figures to show FIFA there is an appetite for women’s football in Australia and a World Cup on home soil will reap huge long-term benefits.

The overall total of close to 2 million people playing football in Australia is also a good indicator that there is a considerable market who will attend a world class footballing event in our backyard.

The Matildas qualified for the Olympics in Japan on Wednesday, a country who is expected to be Australia and New Zealand’s number one rival to host the 2023 Women’s World Cup.

The ball is now in FIFA’s court, with a host announcement to be made in June.
Previous ArticleNext Article

The A-League has a visibility problem and only Network 10 can fix it

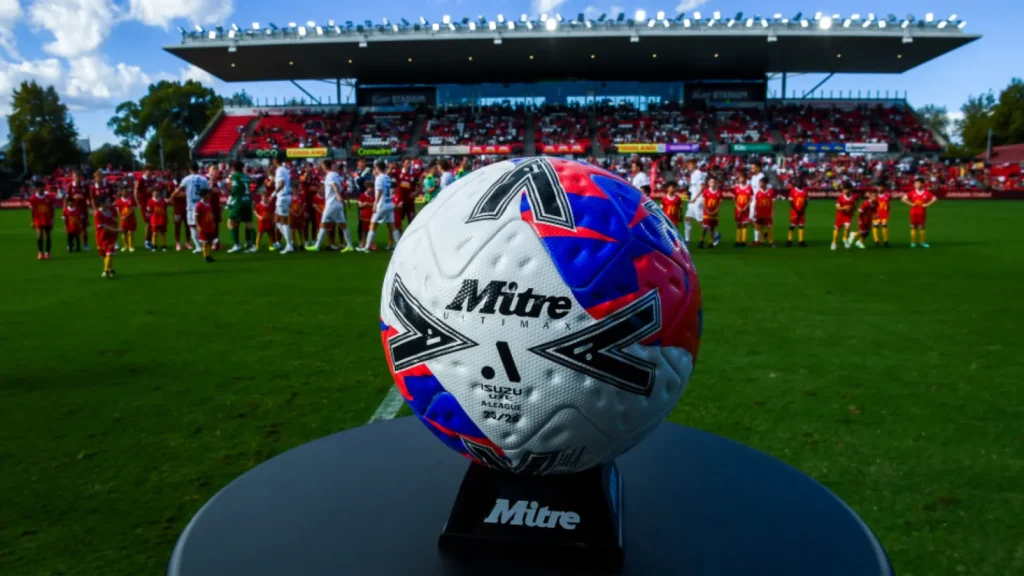
The A-Leagues are just over a month away and with the final stages of the Australia Cup in progress, attention should be firmly turning towards Australian football. Instead, there is a familiar problem. The domestic game once again is struggling to cut through.

The A-Leagues recently secured a three-year extension with Paramount+ and Network 10. The agreement keeps every A-League Men’s and Women’s match on Paramount+, while the free-to-air broadcaster will show one men’s match each week. Following on from their initial five-year deal signed in 202, it’s great that the partnership appears in it for the long haul.

But the big question remains: why is the product not being sold to audiences loudly on the eve of the season? Where is the noise?

Stan Sport and the Nine Network’s Premier League has shown what can happen when a broadcaster actively promotes its football product. The A-League has good numbers in places – one in seven Australians claim to support an A-League team – but the product lacks the exposure it deserves with less than 7% of Australians actively watching the league. It rarely feels like a major sporting product.

The A-Leagues’ current deal

Network 10 and Paramount+ have invested heavily in Australian football. The previous deal before the three-year extension (signed 2021) cost the broadcasters $40 million per year.  A-League viewing on Paramount+ reached record levels in 2025/26 – viewing was up 55 per cent compared with 2021/22. The 2025/26 season reached 4.1 million live viewers.

Those numbers should be celebrated. But those successes are dependent on viewers signing up and tuning into the streaming service of Paramount+. The competition does not receive continual exposure across the Network 10 ecosystem. One men’s match is shown free-to-air each week. That is the contractual commitment. Many of those matches are pushed onto secondary channels rather than the main network.

The Premier League, whilst being a very different product, is receiving much more attention from its Australian broadcasters. Despite being hosted as late as 2:30am, it still receives a massive marketing boost. Stan Sports’ newest campaign boasts flashy billboards in major cities with stars such as Erling Haaland and Bruno Fernandes. Meanwhile, the A-League sits in the corner.

Nine is reportedly prepared to spend up to $860 million over six years to retain the Premier League beyond its current deal, which expires at the end of the 2027/28 season. That would be roughly $145 million per year. There is a reason Nine is willing to make that investment.

Since taking over the Premier League, Stan Sport subscriptions have increased by 40 per cent. Nine very rarely puts the Premier League on free-to-air; marquee matches such as Manchester City against Tottenham Hotspur in 2025 saw a total reach of 1.1 million. That’s nearly 14% of the A-League’s total yearly viewership.

I understand the talent discrepancy, but the lack of broadcast investment to make people aware of the local competitions, and the everyday fan’s ability to access them, is significant in contrast to the Premier League. 

Competition is getting smarter

The A-Leagues are not operating in a vacuum. Australian sport is becoming increasingly aggressive about broadcast exposure. The AFL’s current seven-year broadcast agreement is worth $4.5 billion.

These top-end agreements are not realistic for the A-League, but perhaps more relevant comparisons are Australian basketball’s NBL and cricket’s Big Bash.

Basketball has a similar challenge to football, competing for attention in summer. Its clubs are concentrated in major Australian cities, and also rely on younger audiences and digital engagement to drive growth. During the 2025/26 season, average audiences on Network 10’s primary channel increased by 18 per cent and the NBL’s 2026 finals coverage increased viewership by 36 per cent.

Importantly, all NBL finals coverage was shown on the main 10 channel as opposed to regular season games on 10 Bold and 10 Peach. Then came a major strategic move. Having been with Network 10 since 2021, the NBL chose not to renew its contract and went to market.

While the NBL’s streaming rights have remained with ESPN (primarily owned by Walt Disney Co.), Channel Nine swooped to buy the free-to-air NBL rights for the upcoming 2026/27 season. They’ll show two matches each week, with marquee games to appear on Channel 9.

The deal also includes a weekly studio program, a dedicated 9Now hub and broader promotion through Wide World of Sports. This is in direct competition with the A-League. Not only will both have free-to-air matches on Saturday nights, but access to more content from beyond the sport will be available for free.

The BBL provides another useful comparison. Under Cricket Australia’s current agreement, Seven and 7plus show 33 of the 43 BBL matches, including three finals. On average, that is at  least three-to-four free games a week.

The point is not that every A-League match needs to be on a major free-to-air channel. It cannot realistically achieve that. But despite the A-League’s broadcasters investing big in Australian football, they’ve still been drowned out when compared to Stan and the Premier League. Meanwhile, the average Australian does not have the same access to the A-League as established competitions such as the AFL. 

The BBL has four games a week free, the AFL has three, the NBL two. The A-League languishes behind with a single game. Not only does it hurt diehards, but it stunts any growth from the casual fan.

What the A-Leagues need to do

The A-Leagues are now tied to Paramount+ and Network 10 for another three years. That makes the next step obvious. The league needs to make the most of the partnership. Simply, the broadcasters have to be doing more.

Accessibility is the key. Network 10 has to be actively promoting the A-League with free-to-air shows that have analysis. 10’s free app and Paramount+ must make the A-League the first thing you see.

Football Australia has done great things with the Australia Cup. Select matches are available free through Football Australia’s YouTube channel alongside coverage on Network 10 and Paramount+. That is smart and will attract casual audiences, without asking them to invest financially.

But the pressure also has to fall on Network 10. If they’ve invested in Australian football for the long term, they need to support the investment properly. Promote games days prior to kick-off; cover the game’s stories even during the off-season. If Network 10 and Paramount want a return on their investment it is in their best interest to have the sport be a consistent and routine presence. 

The A-League does not necessarily need another broadcast deal. It needs a broadcaster that invests and believes in the product it spent so much to secure. The football is there, and audiences are growing. Now the promotion needs to match the ambition.

Europe Is Packing Out Stadiums – Is Australia Missing the Bigger Picture?

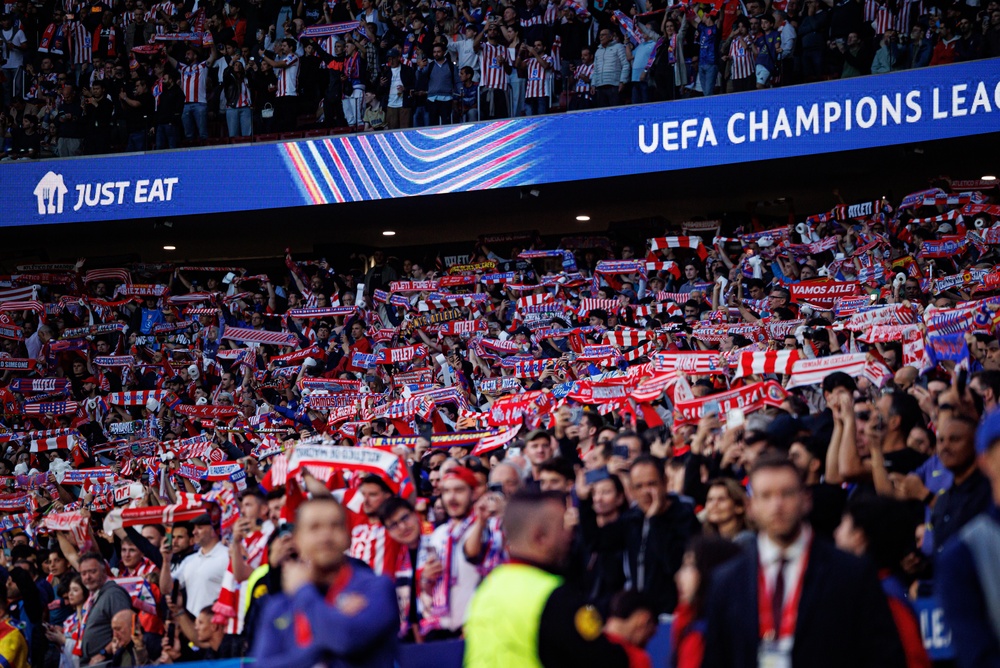
More than 60 million fans attended matches across Europe’s five major domestic leagues during the 2025/26 season, with average attendances rising 2.4 per cent to 34,402 spectators per game.

On the surface, the figures paint a picture of a healthy ecosystem. Stadiums are fuller than ever, supporters continue to attend in large numbers and live football remains one of the most compelling entertainment products in the world.

But headline crowd figures only tell part of the story.

The more revealing measure is stadium utilisation how much of a venue’s capacity is actually being filled and the structural factors influencing those numbers.

For clubs, higher attendances don’t simply mean more ticket sales. Every additional supporter creates revenue opportunities across hospitality, food and beverage, merchandise and memberships. Modern stadiums are increasingly designed to maximise revenue per visitor, making infrastructure investment as much a commercial decision as a football one.

Attendance growth needs context

In Germany, the Bundesliga reclaimed its position as Europe’s best-attended league, averaging more than 42,300 spectators per match following a 9.4 per cent increase on last year’s figures.

However, much of that growth was driven by the return of traditional powerhouses Hamburger SV and 1. FC Köln. Both clubs continued to attract crowds of more than 50,000 despite spending recent seasons in the second division.

Their promotion didn’t suddenly create new supporters.

It returned two of German football’s biggest fan bases to the top flight, demonstrating how promotion and relegation can significantly influence league-wide attendance trends.

Everton shows how new stadiums can unlock demand

While the Premier League recorded another increase in average attendance, much of that growth can be traced to Everton’s move into the new Hill Dickinson Stadium. The larger venue added almost 13,000 spectators per home match compared with Goodison Park, accounting for more than half of the league’s overall attendance growth during the season.

Rather than generating new demand, the project unlocked demand that already existed.

That distinction matters.

Attendance should be viewed alongside stadium utilisation because many clubs have effectively reached capacity.

A stadium averaging 98 per cent capacity tells a very different story to one averaging 60 per cent, even if the latter attracts more spectators overall.

High utilisation suggests strong demand, pricing power and a compelling matchday experience, while lower utilisation can indicate untapped potential or a venue unfit for its market.

Capacity is becoming a strategic issue

In competitions where grounds are regularly close to full, future growth will depend less on attracting new supporters and more on expanding or redeveloping stadiums.

Elsewhere, the opportunity lies in making better use of existing capacity.

Spain illustrates how infrastructure can also temporarily suppress attendances. Barcelona’s continued absence from the Spotify Camp Nou during its redevelopment has limited crowd numbers despite strong demand.

Real Madrid’s renovated Santiago Bernabéu, meanwhile, demonstrates how modern stadium investment can increase not only capacity but also commercial revenue through premium hospitality.

League structures also shape attendance trends

Ligue 1’s growth over recent seasons has coincided with its reduction from 20 clubs to 18, concentrating a greater number of well-supported clubs within the competition and lifting average attendances as a result.

Stadium investment, league composition, promotion and relegation, and long-term supporter culture all play a role.

Taken together, the figures suggest that attendance growth is rarely driven by a single factor.

The lesson for Australian football

Crowd figures are often viewed as the primary indicator of a league’s health, but European football demonstrates that context matters just as much as the headline number.

The recent Australia Cup fixture between South Melbourne and Preston Lions provides a good local example. While the official attendance was 6,673, the packed grandstands, active supporter groups and television presentation created an atmosphere that felt far larger than the raw figure suggested.

It was a reminder that fan engagement, venue utilisation and matchday experience can often say more about the health of a competition than attendance alone.

A sold-out 15,000-seat stadium may indicate stronger demand than a half-full 30,000-seat venue, while investment in infrastructure can unlock thousands of additional supporters without changing underlying interest in the game itself.

As clubs continue to invest in new stadiums and redevelop existing venues, attendance should increasingly be measured not simply by how many people are watching, but by how effectively football is meeting supporter demand.

The crowds may be rising, but the real story is why.

Most Popular Topics

Editor Picks

Send this to a friend